At the roof
Impacts, creases, missing material and opened connections inform the work needed. Normal wear and previous repairs also matter.
Understand roof findings, covered scope and the payment terms that affect a storm-damage decision.
Free roof inspections. Repairs, replacements and commercial roof help.
Roof damage, repair scope and an insurance payment are separate parts of the same problem. Understand what the assessment can show and which policy terms affect what you pay.
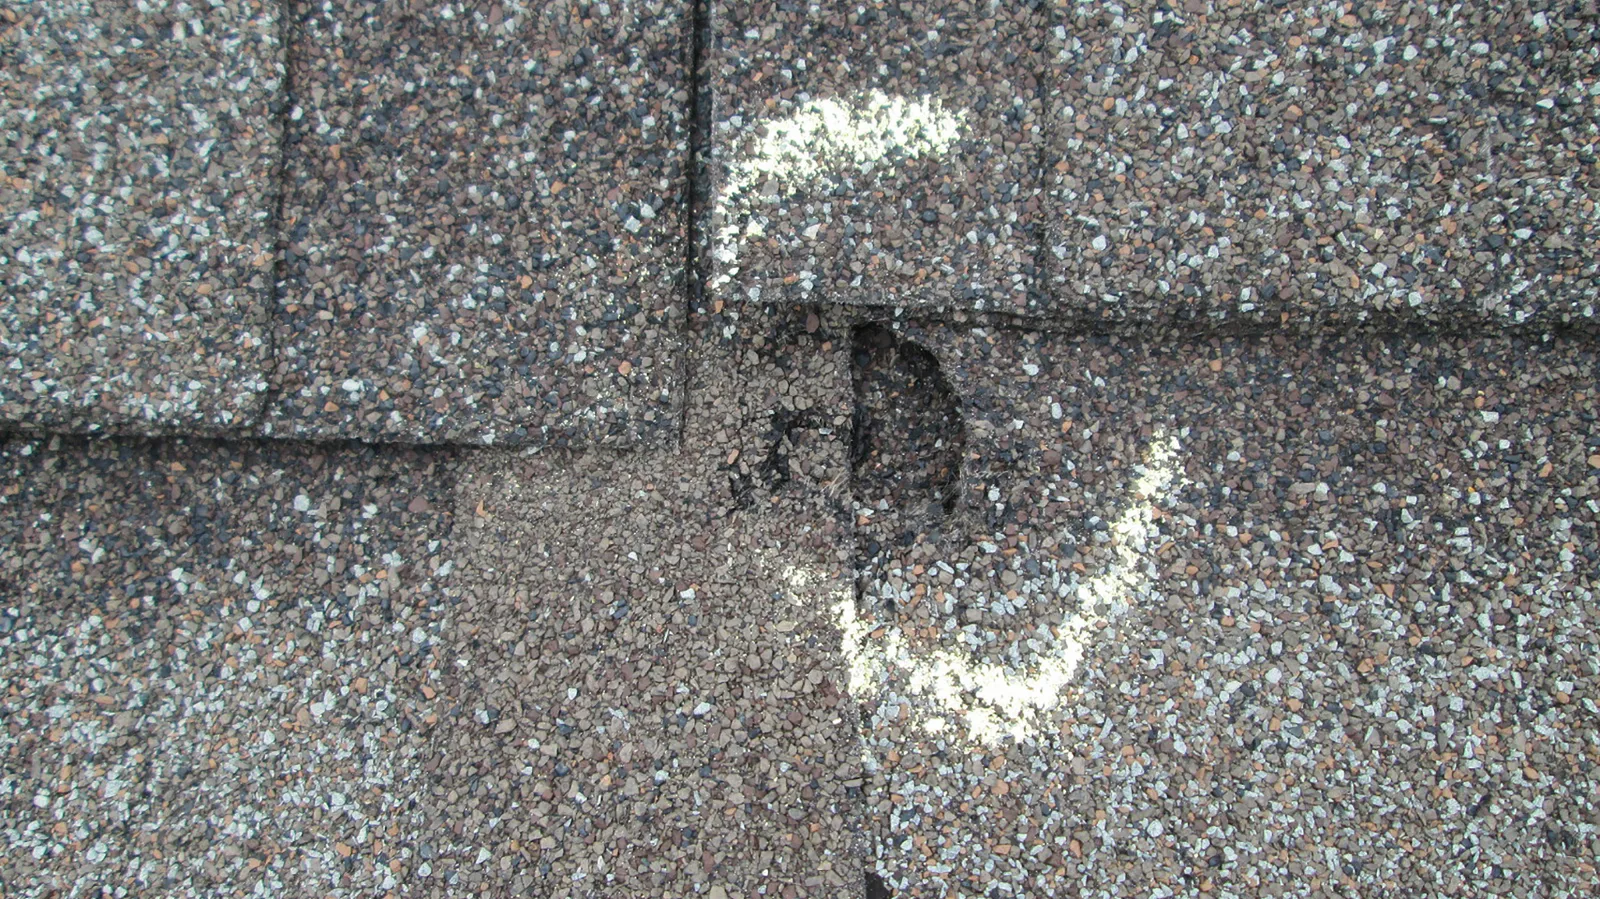
The property’s roof condition needs its own assessment.
Impacts, creases, missing material and opened connections inform the work needed. Normal wear and previous repairs also matter.
A storm report documents an observation at a stated time and place. It does not establish damage or causation at every nearby property.
The insurer applies the policy to the reported cause and covered work. A roof inspection does not promise claim approval or a full replacement payment.
Missouri insurance guidance distinguishes these concepts. The actual policy can apply different roof terms than other dwelling terms.
| Term | What it changes |
|---|---|
| Deductible | The policyholder’s share of a covered loss. It can be a stated amount or subject to policy-specific calculation. |
| Actual cash value (ACV) | Payment accounts for depreciation under the applicable terms. That can leave more of the replacement cost with the owner. |
| Replacement cost value (RCV) | Covered repair or replacement without depreciation, subject to the policy’s conditions, limits, deductible and payment process. |
| Covered scope | Only the covered work is part of the claim. Upgrades or unrelated deterioration can affect what remains the owner’s responsibility. |
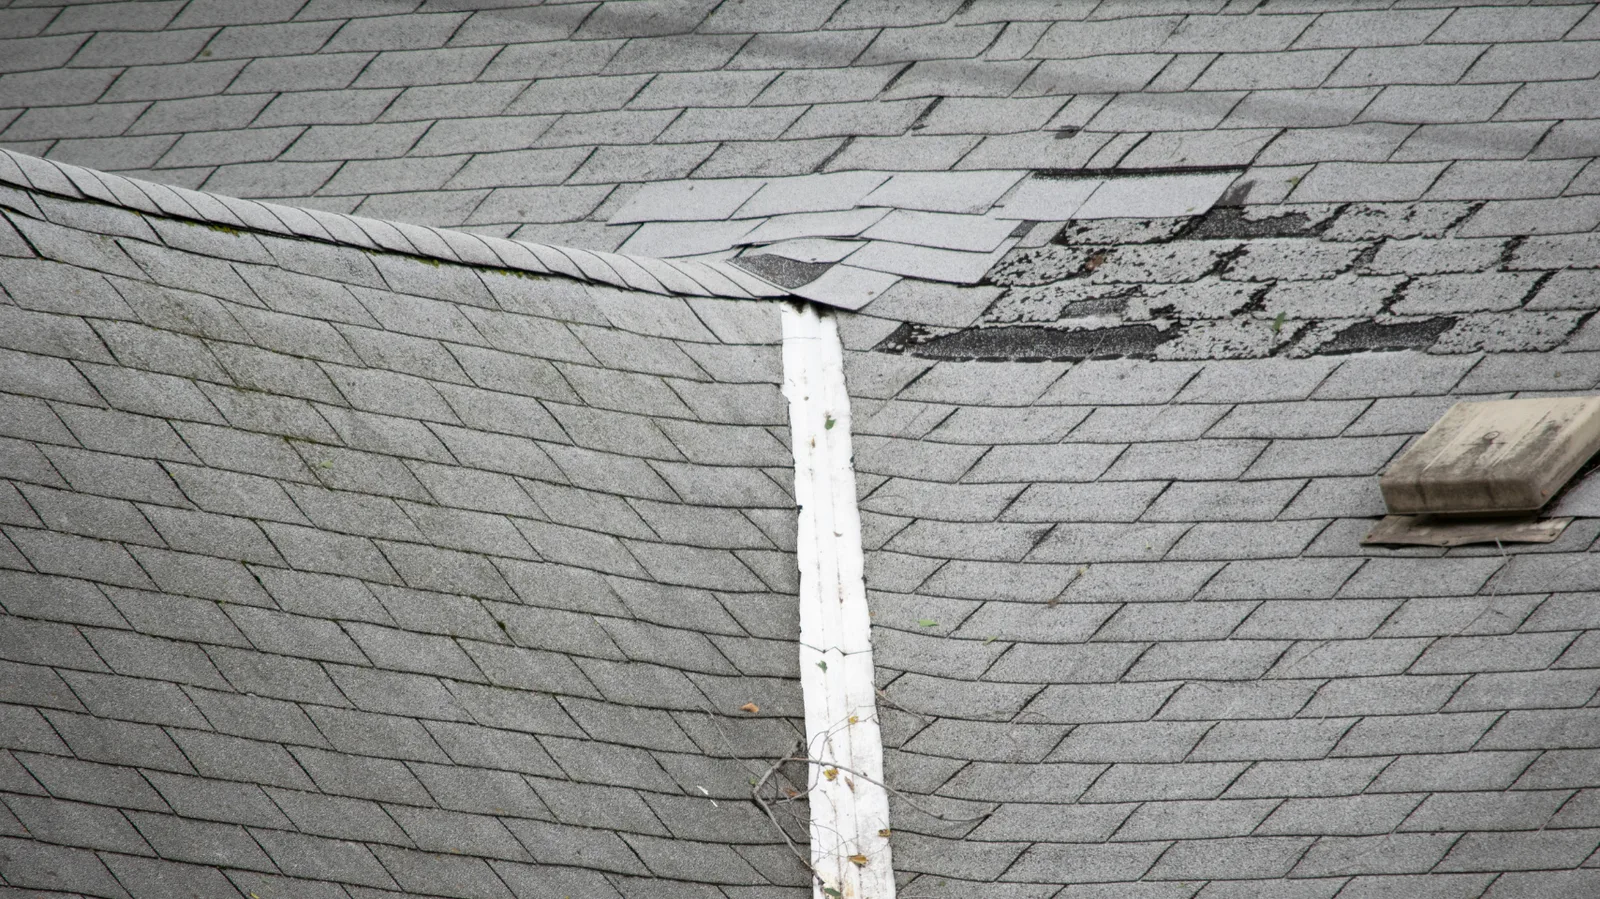
Safety and protection come first; the policy and the physical work then need separate attention.
Stay away from damaged roof areas, sagging ceilings and electrical hazards. Tell the roofer if water is coming in now, and report a potential covered loss promptly to the insurer.
The roof condition informs repair or replacement. Temporary protection and permanent reconstruction have different purposes.
The insurer’s covered scope, deductible and valuation process determine the payment. Replacement-cost claims can have completion conditions before remaining amounts are paid.
The Missouri Department of Insurance explains roof coverage, replacement cost and actual cash value. Policy wording and the facts of the loss govern the actual claim.
No. Missouri insurance guidance says roof repair or replacement depends on damage from a covered peril. Age and normal deterioration do not by themselves establish that claim.
No. Depreciation, uncovered work, policy limits, exclusions and upgrades can affect the amount the owner pays. The actual policy and covered scope determine that answer.
Tell us what changed at the Liberty property and roughly when. A free inspection helps establish the roof work under discussion.
Liberty Roof Pros